If you’ve been watching the market from the sidelines, you’ve probably noticed it hasn’t done you any favors lately. Homes that are priced right are still getting attention, and buyers who come prepared are the ones walking away with the win. I talk with a lot of buyers who are waiting for rates to drop and prices to soften at the same time. It’s an understandable hope. But when rates do come down, the buyers who have been sitting on the sidelines tend to come back all at once, competition picks up, and prices often follow. The perfect combination rarely shows up, and when it does, you’ll likely have plenty of company.
So here’s the question I’d ask: if you’re waiting for the ideal mix of rates and prices, how many more years older will you be when it arrives? We all have to live somewhere. Life goes on while we wait.
Rates are such a big part of the story. Mortgage rates recently rose above 7% for the first time since January 2025, with Freddie Mac reporting a 30-year fixed average of 7.03% on September 24. A year ago at this time, that average was 6.30%. That difference shows up every month. On a $500,000 home with 10% down, a single percentage point in rate can mean roughly $300 a month in principal and interest. That’s real money, and it’s worth taking seriously.
Don’t Plan on “Just Refinancing”
And another thing. My opinion is that if you can afford the payment, you should buy the property. But PLEASE don’t stretch into something you can’t afford because you’re counting on refinancing when rates improve. With inflation proving sticky and the Federal Reserve moving in the other direction, I don’t see us going back to 4% anytime soon. If a refinance opportunity comes along down the road, treat it as a bonus, not the plan.
Have the Real Conversation
What I’d encourage instead is a solid conversation about affordability, and your lender should be part of it. A good lender can walk you through options you might not have considered: how much to put down, whether to buy down your rate, which loan programs fit your situation, and what your payment looks like under each scenario. Then you can decide, with real numbers in front of you, whether now is the right time for you to buy. It’s a strategy, not a guess.
What I Told My Son
A few years ago, my oldest son was living in a third-floor apartment with no charm, no room for future growth (and no air conditioning), waiting for something. I’m still not entirely sure what. So I did what any real estate broker step-mother would do: I met him for lunch with charts and graphs about payments.
We sat down with his lender and worked out a plan to make his payment comfortable. Instead of putting all his savings toward the down payment, he used part of it to buy his rate down for the life of the loan. That one decision made his monthly payment something he could live with.
He was reluctant at first. I did an OK job of explaining YOLO to a young person, and I told him this: two or three years from now, you can be living in a modest home that you improve over time, building value as you go. Or you can still be living at 112 Main Street along with 12 other renters.
He’s now been in his home for three years. He’s done a great job with his little house, making it his own one project at a time, and it makes me so happy to see how much he enjoys being there and having a place of his own that he can make changes to, chip away at the principal balance, and make financial progress.
The Bottom Line
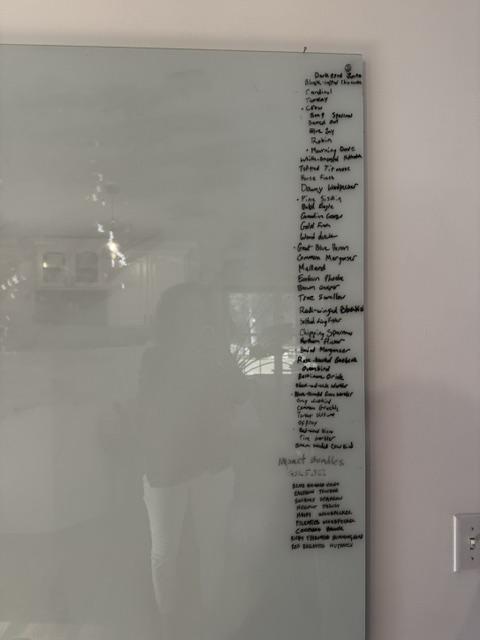
Rates and prices will keep moving, and nobody can time them perfectly. What you can control is whether the payment works for your life right now. If it does, and you’ve done the homework with your lender, the right home may be closer than you think. I frequently connect buyers with top lenders, and am happy to suggest a few for you to consider, so that we can move on to seeing properties that might be a match for you. And the photo that accompanies this story? It’s a wall-mounted glass board seen at a recent showing with a buyer who wanted a home that’s away from it all. The sellers maintain a list of birds they’ve seen on the expansive property. That quality of life, if it’s what you’re looking for, and is worth paying for if you can afford it. Because we’ve all just got one go-around.
As always, reach out for anything real estate related — or anything local you think I might be a resource for. I’m here, I’m busy, and I’m happy to help.
If you’d like to talk about getting your home ready to sell, considering multi-generational living, should you stay or should you sell, figuring out the right ownership structure, or finding a good home for that wedding dress — I am genuinely local, genuinely accessible, and I have a lengthy track record of extremely satisfied clients–both buyers and sellers. If you, or anyone you know, are moving to (or from) Central Massachusetts, I’m here to deliver an exceptional experience. My team combines strong communication, proven strategies and deep local expertise to guide throughout the home selling and buying process. If you’re considering the purchase or sale of residential real estate, you owe it to yourself to have a confidential conversation with me.
Jennifer Shenk, Real Estate Broker
Keller Williams Realty North Central
107 Main Street, Westminster
Call/Text: 978 870 9260